

Greetings. Several months ago, in Journal #22, I argued that the AI ecosystem should be understood based on Jensen’s five-layer cake: powers, chips, data centers, LLMs, and applications. My conclusion was not that every layer looked equally attractive. It was almost the opposite.
Applications were in the “too hard” pile. LLMs looked increasingly crowded, especially as open-source models from China continued to improve at lower cost. The data-center layer, by contrast, looked more interesting. It required enormous capital, faced real physical bottlenecks, and sat underneath almost every possible winner above it.
That led to the obvious question: what does the kitchen actually earn? With the AI giants now funding the build-out with debt and equity, that one number - ROIC - may decide whether the AI capex boom is rational or reckless.
For most of the AI build-out, that question has been nearly impossible to answer. Microsoft, Amazon, Google, Meta, and Oracle disclose total capex, cloud revenue, operating income, and depreciation. But they do not give us a clean line item that says: this pile of GPUs cost this much and generates this much revenue.
Two unusual xAI compute contracts now give us a cleaner window. The disclosures come from SpaceX IPO-related SEC filings, not from xAI, Google, or Anthropic operating reports, so they should be read as SEC-filed summaries from a company with an incentive to show the value of its compute assets. Still, they contain the pieces we rarely get in one place: a stated contract price, a known GPU count, a contract term, and enough information to estimate the capital base.
This is not an industry-average ROIC calculation. It is a case study of the cleanest disclosed AI-compute contracts we currently have.
The Two Compute Contracts
Both contracts come from the same place. xAI built an enormous AI computing site in Memphis, nicknamed Colossus, to support Grok and other internal workloads. But the site appears to have more capacity than xAI needed immediately, so SpaceX/xAI began selling access to some of that compute capacity to third parties.
• Google buys compute from xAI. Google pays about $920 million a month - roughly $11 billion a year - for access to approximately 110,000 Nvidia GPUs, plus CPUs, memory, and related components. The filing does not specify the GPU models. It says Nvidia GPUs; it does not say they are the newest Nvidia systems.
• Anthropic buys compute from xAI. Anthropic pays about $1.25 billion a month — roughly $15 billion a year — for a larger and broader footprint. xAI’s May 6 announcement described Colossus 1 as having more than 220,000 Nvidia GPUs, including H100, H200, and GB200 systems. SpaceX’s June 4 IPO-related UK Retail Offer Disclosure Summary later described the Anthropic agreements as covering roughly 325,000 Nvidia GPUs across Colossus and Colossus II. I use the 325,000 figure because it is the broader contract-disclosure number, but I do not assume all of that capacity is live on day one or made up of the newest Nvidia systems.
One more detail deserves precision up front. The Google contract runs from October 2026 through June 2029 - 33 months, or just under three years - with capacity ramping through September 2026 at a reduced fee. After December 31, 2026, either side can terminate on 90 days’ notice. Anthropic’s agreement similarly runs on paper through May 2029, with ramp-up in May and June 2026 and 90-day termination rights after the initial three-month period.
Sources: SpaceX Rule 433 free writing prospectus for the Google Cloud Service Agreement, filed June 5, 2026; SpaceX Form S-1 / amended S-1 disclosures regarding Anthropic, and SpaceX Rule 433 UK Retail Offer Disclosure Summary filed June 4, 2026.
Two observations matter
First, these are not risk-free annuities. Even the Anthropic contract is better understood as a high monthly contract stream than a permanent marriage. Either side can reportedly walk away after a short notice period. So “tens of billions over several years” is really “a very large monthly check that can stop in a quarter.”
Second, the credit quality of the customers is not the same. Google is one of the strongest payers in the world. Anthropic is a young AI company with extraordinary growth but heavy cash burn. The Anthropic revenue is only as reliable as its financing runway.
One more caveat matters: the revenue side is current contract revenue, not normalized long-term revenue. These are scarcity-era compute prices. If supply catches up, renewal rates will almost certainly be lower. So the right question is not whether today’s ROIC lasts forever. The right question is whether the starting return is high enough to absorb that risk and still justify the build-out.
What It Costs to Build
To judge the return, I first need to estimate what it cost to build the computing capacity being sold.
The cleanest way to think about these sites is not just “how many chips,” but “how much power.” Everything scales with power: chips, racks, networking, cooling, electrical equipment, buildings, backup systems, and the connection to the grid. The industry measures that in megawatts and gigawatts. One gigawatt is 1,000 megawatts - roughly the output of a large power plant.
For this exercise, I use a rough all-in cost of $50 billion per gigawatt of modern AI compute.
That number is not xAI’s disclosed build cost. It is a deliberately conservative replacement-cost assumption - closer to what one might use for a latest-generation frontier AI build than for a mixed fleet of older and newer GPUs.
The public anchors are useful. Goldman Sachs’ AI infrastructure framework assumes 1.2 PUE, $15 million per megawatt for the data-center shell, and $2,500 per kilowatt for new power infrastructure. Goldman also notes that next-generation AI data centers increasingly fall in the $15 million to $20 million per megawatt range before the chips. Epoch AI separately estimates that a typical one-gigawatt AI data center using Nvidia GB200 NVL72 systems requires about $38 billion of upfront capital expenditure.
Sources for the $50B/GW framework: Goldman Sachs Global Institute, “Tracking Trillions: The Assumptions Shaping the Scale of the AI Build-Out,” May 2026; Epoch AI, “Servers account for 60% of the total cost of ownership of a one-gigawatt AI data center,” May 2026.
Start with those anchors. Then add conservatism for frontier systems, networking, redundancy, land, power equipment, execution risk, and recent memory-cost inflation. That is how I get to $50 billion per gigawatt. It is not meant to be precise to the decimal. It is meant to be a hard denominator. If the returns still work using a high capital base, the conclusion is stronger.
This conservative framing matters because the xAI fleet does not appear to be a pure latest-generation build. xAI has described Colossus 1 as including Nvidia H100, H200, and GB200 accelerators. SpaceX’s June 4 UK Retail Offer Disclosure Summary describes the Anthropic agreements as covering roughly 325,000 Nvidia GPUs across Colossus and Colossus II, but does not specify the exact model mix or whether all of that capacity is live on day one. The Google filing similarly discloses access to roughly 110,000 Nvidia GPUs, but does not identify the GPU models.
If some of these GPUs are older than the newest frontier systems, the true capital cost would likely be lower than $50 billion per gigawatt. That would raise the return, not lower it. In other words, the test is conservative by design.
Scaled down, the arithmetic is simple: $50 billion per gigawatt means $5 billion per 100 megawatts. Strictly applied, 250 megawatts costs $12.5 billion, 300 megawatts costs $15 billion, and 420 megawatts costs $21 billion.
• Google’s slice - about 110,000 Nvidia GPUs - likely draws roughly a quarter of a gigawatt. At $50 billion per gigawatt, that implies about $12.5 billion of capital. I use $15 billion in the return table anyway, which is equivalent to assuming closer to 300 megawatts or adding a conservative buffer. That is intentionally harsh. If Google is receiving older or lower-cost GPUs, the true capital base would be lower and the ROIC would be higher.
• Anthropic’s slice is larger. To keep the test conservative, I use a $21 billion capital base, equivalent to roughly 420 megawatts at $50 billion per gigawatt. That is not a claim that the disclosed power draw is exactly 420 megawatts. It is simply the capital base I use for the return calculation. Given that the fleet appears to include a mix of GPU generations, this is again meant to be a conservative denominator, not a precise engineering estimate.
From Contract Revenue to Operating Profit
Start with Google because it is the simpler example.
At full ramp, Google pays xAI $920 million per month for access to AI compute capacity. That is about $11.0 billion a year of contract revenue.
The first cost is operating the site. Electricity, cooling, maintenance, networking operations, and staff are real expenses, but they are small compared with the contract revenue and the chips. I estimate about $0.7 billion a year for Google’s slice. That leaves about $10.3 billion of cash operating profit before depreciation.
The second cost is depreciation - the gradual economic wear-and-tear of the chips.
Depreciation is simply how we recognize that chips lose economic value over time as newer hardware arrives and contract prices change.
For this article, I use a four-year depreciation life. That is not because either contract lasts exactly four years. They do not. I use four years because the asset does not disappear when the first contract ends.
Using a $15 billion capital base for Google’s slice, four-year depreciation equals $3.75 billion a year. Subtract that from $10.3 billion of cash operating profit, and the Google deal produces about $6.55 billion of operating profit a year.
Anthropic works the same way, just at a larger scale. Its annual contract revenue is about $15.0 billion. I estimate annual running costs at about $1.25 billion, leaving $13.75 billion of cash operating profit before depreciation. Using a $21 billion capital base, four-year depreciation equals $5.25 billion a year. That leaves about $8.5 billion of operating profit.
The Answer to the Trillion-Dollar Question
With those assumptions, the ROIC calculation is straightforward. The table below shows the bridge from annual contract revenue to operating profit and return on invested capital.
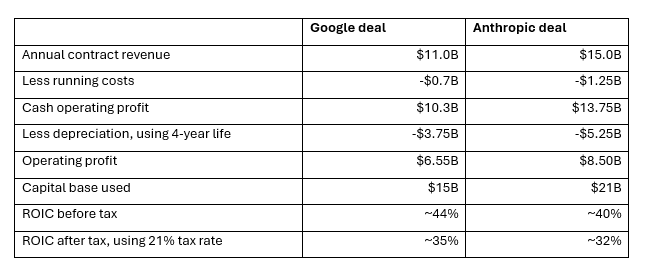
The conclusion is hard to ignore: even using a capital base that is probably too high, both deals still appear to earn around 40% before tax and low-30s after tax.
That is the important point. The return is not being manufactured by a generous capital-cost assumption. The capital base is deliberately high, and the four-year depreciation life is not aggressive.
Why This One Number Now Decides Everything
Goldman Sachs recently framed the AI build-out as a multi-trillion-dollar infrastructure cycle. In its “Tracking Trillions” report, Goldman’s baseline case estimates roughly $7.6 trillion of AI infrastructure spending from 2026 through 2031 cumulatively, across compute, data centers, and power. Annual spending rises from roughly $765 billion in 2026 to about $1.6 trillion by 2031.
The chart below captures the scale of the question.
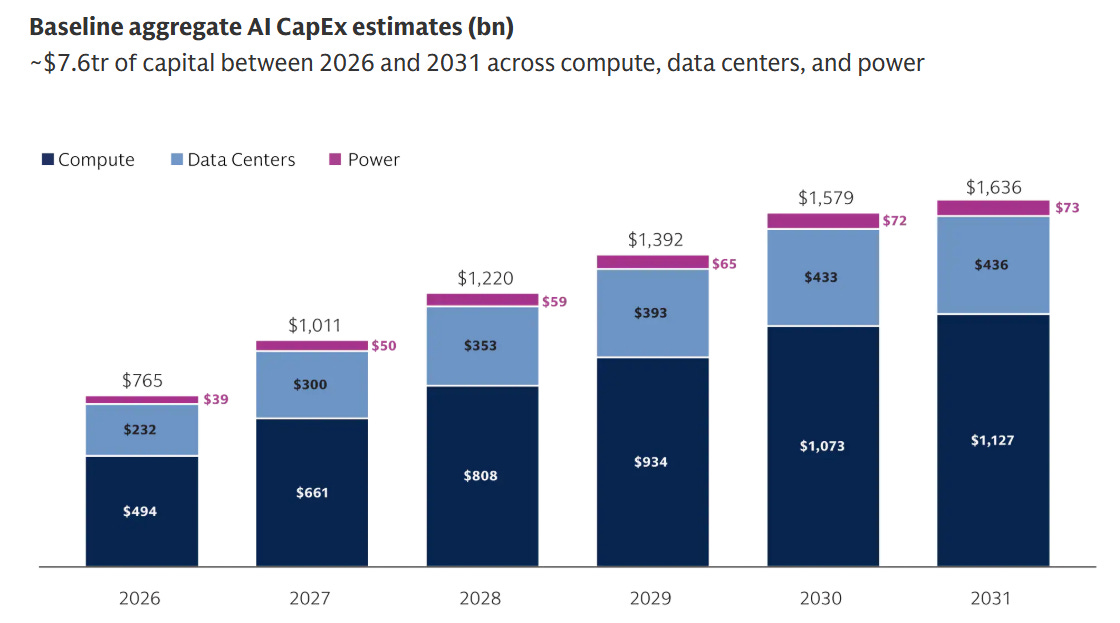
Source: Goldman Sachs Global Institute, “Tracking Trillions: The Assumptions Shaping the Scale of the AI Build-Out,” May 2026. Baseline aggregate AI CapEx estimates across compute, data centers, and power. Forecasts and expectations are based on material assumptions subject to change.
This is no longer just a question of spending spare cash. Alphabet recently raised about $85 billion of equity to fund AI infrastructure, including a $10 billion investment from Berkshire Hathaway, after already raising more than $85 billion of debt over the prior year. Meta has also tapped the bond market heavily, including a $25 billion bond sale this year after a record $30 billion bond sale last year. The point is not that these companies are financially weak. They are not. The point is that the AI build-out is now large enough that even the strongest companies are using outside capital to fund it.
That changes the question. Once debt and equity enter the picture, ROIC stops being an academic metric. Borrowed money has a cost. New shares dilute existing owners. Neither is a problem if the capital earns a high return. Both become a problem if the return falls below the cost of capital.
My rough line in the sand is 25% pre-tax ROIC. That is not a scientific number. It is a practical hurdle that sits comfortably above debt costs and the likely required return on equity. If a new AI data center can earn 30% to 40% pre-tax ROIC, then issuing debt and even some equity may be entirely rational. A company should raise outside capital when it can reinvest that capital at very high rates of return. That is not financial weakness. That is good capital allocation.
But the reverse is also true. If contract prices fall, utilization drops, or GPUs go dark, the same financing becomes dangerous. Debt that looked cheap becomes a burden. Equity issuance that looked opportunistic becomes dilution. The capex boom then shifts from strategic necessity to capital misallocation.
That is why these two xAI compute contracts matter. They are not perfect. They are not long-term guarantees. They may partly reflect a temporary shortage of AI compute. But they are among the cleanest disclosed examples we have of what large-scale AI compute actually earns.
Using a conservative capital base and four-year depreciation, the Google and Anthropic deals appear to earn roughly 40% pre-tax ROIC. That is well above my 25% threshold, even before considering that the actual build cost may be lower than the conservative $50 billion-per-gigawatt framework used here. So I am not ready to call the AI capex cycle a bubble. Not yet.
The better conclusion is more conditional: as long as new AI data centers can earn returns anywhere close to these disclosed xAI contracts, the hyperscalers are probably justified in continuing to build, even if that means issuing debt or equity. But this is now the line in the sand. The day the best observable AI compute deals stop clearing that return threshold is the day the story changes.
Until then, the kitchen still earns its keep. As always, thanks for reading - and keep it in the short grass.
your estimate for operating costs (Electricity, cooling, maintenance, networking operations, and staff) are wrong